Long / Short Equity · Net Long Bias

Deep analysis on high-quality growth.

We invest in emerging microcaps and established compounders, and short businesses driven more by narrative than fundamentals — built for limited partners who think in decades, not quarters.

2013Manager track record begins
1.5% / 15%Below-average fees, 5% hurdle
120–150%Target gross exposure, 60–90% net
QuarterlyLiquidity after 12-month lockup

Strategy

We exploit the market's mispricing of long-duration quality growth.

Every position is underwritten against our Four Pillars, then sized by projected three-year IRR, recalculated weekly.

Core · Microcaps

Emerging Growth

High-growth, under-the-radar businesses below $1b, found before the market notices them — where thin coverage leaves the widest mispricing.

Kraken Robotics · Shelly Group · Cellebrite · Hydreight

Core · Compounders

Established Growth

Moat-protected, high-ROIC businesses that keep compounding profitably for a decade or more. Quality persists, and we hold it.

MercadoLibre · Arista Networks · Topicus · Vertiv

Opportunistic

Special Situations

Timing-specific setups — spin-offs, holdco discounts, short squeezes, pre-announcement M&A — deployed selectively for uncorrelated alpha.

IDT · Liberty Sirius · TRUBAR

Alpha + hedge

Short Book

Potential frauds, broken business models, industry fads and lockup overhangs. Never on valuation alone; never naked calls.

Nikola · Beyond Meat · Rumble · Quantum Corp

Our Framework

The Four Pillars of an Exceptional Investment.

Every long position is underwritten against the same four tests. The framework draws on Chuck Akre's three-legged stool, Tom Gayner's four investment principles, Chris Mayer's 100 Baggers and Michael Mauboussin's work on moats and returns on capital, adapted for a growth investor.

01

High-quality business model

Quality is the ability to generate sustainable profits over long periods of time, through downturns and disruptions. It takes two things:

  • A durable moat. Intellectual property, regulatory barriers, switching costs, network effects or embedded technology. It doesn't need to be the widest moat, but it must be stable and unchanging over time.
  • A profitable model. One that keeps delivering above-average returns on invested capital, year after year.
02

Outstanding management

Management sets strategy and allocates capital, and a great team avoids the value-destroyers: costly M&A, empire-building and short-term thinking. We judge teams on what they've delivered, reviewing years of earnings calls against what they promised. We look for leaders who are:

  • Honest and forthcoming with investors, employees and counterparties
  • Deep experts in their own industry's dynamics
  • Focused on execution, and who own the outcomes
  • Disciplined capital allocators focused on value per share
03

Substantial long-term growth prospects

We want to own businesses for many years, partly because deferring capital gains taxes is a powerful compounder. Over long horizons, revenue growth is the largest driver of value creation, so we look for companies that can grow for a decade or more.

  • A clear reason growth will outpace the industry, not just a high historical rate
  • Capital-efficient reinvestment that grows free cash flow per share
  • Scalable models whose margins expand as they grow
04

Reasonable valuation

We invest in growth at a reasonable price. Paying up for quality never means ignoring price: we're buying a future stream of cash flows.

  • Valuation must hold up in both a bull and a bear case
  • DCF is a tool for understanding a business, not an oracle. No one has ever found a 10-bagger with a good DCF model
  • Most models fade growth after year five, which creates opportunity in businesses that keep compounding beyond it

Read the full Four Pillars essay →

Our edge

Two sources of edge, stacked.

Portfolio construction tilts the odds before we pick a single stock. Bottom-up work captures the alpha on top.

Structural advantage

Small-cap skewConcentrated below the cap-weighted Russell 2000 average.
High-ROIC industry focusOnly industries with structurally high historical returns on capital.
High-growth biasAbove-market revenue and earnings growth.
Measured leverage130–150% gross amplifies conviction without proportionally raising net exposure.

Active advantage

Information arbitrageDirect dialogue with management and industry experts.
Coverage gapNames below the sell-side radar are priced less efficiently.
Deep fundamental understandingSector-level ROIC and competitive-landscape expertise.
PatienceA multi-year holding period lets us buy the volatility short-term capital creates.

Industry focus

  • Software
  • Healthcare Info Services
  • Computer Services
  • Technology Equipment
  • Specialty Semiconductors
  • Financial & Business Services
  • Payments
  • Defense
  • Aerospace
  • Medical Instruments
  • Medical Diagnostics
  • Serial Acquirers

Performance

Since launch, net of fees.

Deep Sail Capital Partners LP opened to outside investors on July 1, 2022.

19.5%Annualized net return since launchRussell 2000: 14.2%
0.78Sharpe ratioRussell 2000: 0.58
1.19Sortino ratioRussell 2000: 0.85
0.48Beta to Russell 2000Correlation: 0.41
PeriodDeep Sail (net)Russell 2000Russell Mid Cap GrowthBarclay Equity L/S
2026 YTD-1.6%+13.7%-1.3%+9.3%
2025+34.9%+12.8%+8.7%+13.6%
2024+38.1%+11.5%+28.0%+9.1%
2023+6.8%+16.9%+25.9%+13.7%
2H 2022+7.3%+3.9%+7.2%+0.2%
Annualized19.5%14.2%15.9%10.9%
Annualized alpha vs Russell 200014%vs Russell 2000 Growth: 13%

Deep Sail Capital Partners LP, July 1, 2022 (launch to outside investors) through September 30, 2026. 2H 2022 is a partial period; 2026 is year-to-date. Returns are net of actual fees; fund statistics are calculated on gross returns. Excludes the predecessor incubator vehicle, Westropp Funds LP, managed by Sean Westropp under the same strategy from 2016 to 2021; audited results are available on request. Past performance is not indicative of future results. Investing involves risk, including the possible loss of principal.

Process

From idea to position, in five filters.

1SourcingScreens, other investors, industry insight — filtered for our focus industries.
2Business reviewProducts, segments and the management team.
3Financial reviewMargins, TAM, cash flow and capital allocation.
4Deep analysisCompetitive dynamics, alignment and key risks.
5IRR-ranked sizingThree-year IRR modeled, re-ranked weekly across the book.
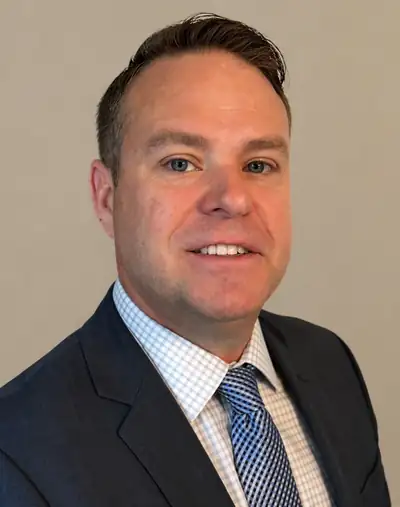
Sean Westropp, Portfolio Manager

Portfolio Manager

Sean Westropp

Sean has managed Deep Sail Capital Partners LP and its predecessor incubator fund since February 2013, moving from a Graham-Dodd value framework to the current high-quality growth strategy in July 2016. Before running the fund full-time he spent 15 years at BP in finance, investment and strategy roles.

EducationMBA, University of Chicago Booth — Analytical Finance & Econometrics
 BS, Purdue University — Chemical Engineering
Experience20+ years in public markets
FeaturedPlanet MicroCap, MicroCap Club, Capital Employed

The Fund

Investor-friendly terms, aligned for 10–20 years.

TermsStandard ClassInstitutional Class
Minimum investment$100,000$500,000
Management fee1.5% (1.0% above $50m AUM)1.0% (0.5% above $50m AUM)
Performance fee15% above 5% hurdle15% above 5% hurdle
High-water markYesYes
Lockup / liquidity12 months, then quarterly (60 days' notice)12 months, then quarterly (60 days' notice)
EligibilityVerified US accredited investors (Rule 506(c)); self-directed IRAs accepted
Fund administratorHC Global
Prime brokerInteractive Brokers
AuditorSpicer Jeffries (Cherry Bekaert)
Legal counselDavis Gillett Mottern & Sims

Investor Inquiries

Let's talk about a long partnership.

We're accepting capital from US accredited investors. Request the investor deck or schedule a call with Sean.